
Xem thêm


 17.09.2026 07:47 AM
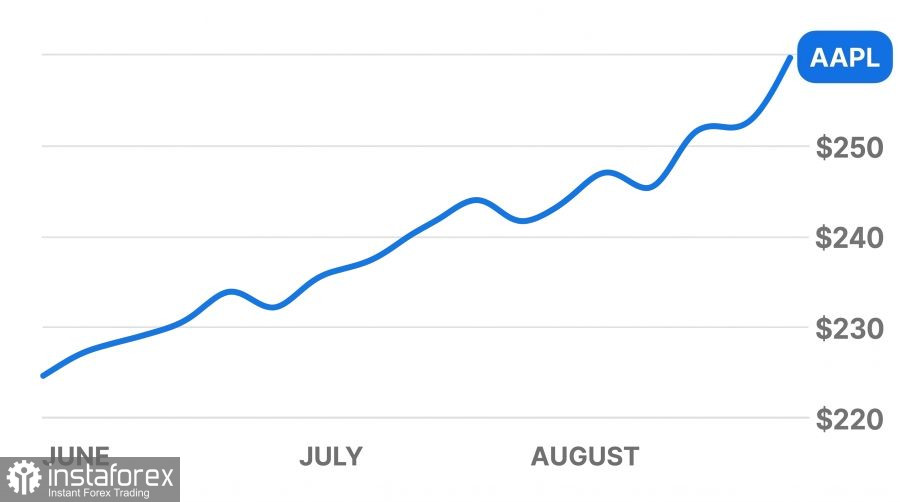
Apple shares closed the trading session at $332.41, up 0.32%, and settled at $333.43 in after-hours trading. The company's stock is currently trading near all-time highs, showing resilience despite sell-offs across other tech giants. The new CEO, John Ternus, kicked off his tenure with a series of major announcements that immediately caught the attention of investment funds and institutional buyers.
Apple is designing its own server for artificial intelligence workloads powered by proprietary M8 Ultra processors, with a launch scheduled for 2029. The company is in talks with Nvidia to utilize its high-speed interconnect system, NVLink Fusion. This technology links boards, chips, and software seamlessly, enabling processors from different makers to exchange data at maximum speed without performance loss. Apple plans server configurations featuring two and four M8 Ultra chips targeted at businesses, developers, and government agencies.
The catalyst for developing in-house servers was an acute shortage of off-the-shelf hardware on the market. In the previous quarter, Mac sales surged by 29% to reach $10.4 billion. This unexpected demand came from AI engineers who began buying up Mac Studio and Mac mini desktops in bulk to train digital models locally in their offices. This quickly depleted warehouse inventory and made it clear that standard consumer hardware cannot handle continuous, round-the-clock server workloads.
At its "Surprise and Shine" event, the company unveiled its first foldable smartphone, the iPhone Duo, starting at $1,999, alongside the iPhone 18 Pro lineup. The new devices run on iOS 27 with an updated Siri voice assistant. The smartphones process basic AI tasks directly on the on-device processor, routing complex computations over the internet to the company's secure servers.
Legal pressure on the company has eased. Startup xAI completely dropped its antitrust lawsuit against Apple, focusing its legal claims solely on OpenAI. Meanwhile, Apple TV took home a record number of Emmy Awards and retained its subscriber base despite the recent subscription price hike. Against this backdrop, investment firm Arete Research raised its price target for Apple shares to $360, and HSBC maintained a "buy" rating with a target of $366 per share.
Despite the rollout of new products and server plans, Apple faces pressure from five market factors:
Our outlook for Apple stock remains more conservative than the targets of Wall Street analysts projecting a rally to $365–$370 per share.
Through September and October 2026, share price growth is likely to pause, giving way to range-bound trading within narrow boundaries. The stock rallied sharply over a short span and has hit resistance at $336.18. With trading volume tapering off, any breakout attempt above this level risks turning into a false rally followed by a swift pullback. If the price breaks below key support at $325, a wave of selling could pull shares down toward the $310–$318 range.
Sentiment around the M8 Ultra server initiative remains largely driven by hype for now. Enterprise-grade server racks won't reach customers before 2029, meaning they will generate no meaningful revenue in the current or upcoming fiscal year. Investors must continue valuing the business on actual smartphone and PC sales, where elevated memory component costs will continue to weigh on net profit.
By late 2026, the stock price should stabilize within the $330 to $345 corridor. Sales of the foldable iPhone Duo should support total revenue, and Apple's status as a safe-haven asset will help shield shares from severe drawdowns. However, 5% yields on US Treasuries and an already stretched price-to-earnings multiple will prevent shares from sustaining a decisive rally above $350. Buying at current peak levels carries elevated risk; waiting for verified fall preorder and sales figures offers a more grounded entry point.

